
Brought to you by…Brex

In the age of AI, finance teams need to move fast while staying in control.
Brex is the intelligent finance platform that gives you the AI-native workflows to move fast (handling receipts, memos, transaction monitoring, policy enforcement, etc) while staying in control and eliminating manual busy work.
Join companies like Anthropic and Zoom that are moving faster because of Brex.
The IPO window seems mostly closed except for the very best AI companies. Also, there are several public tech companies that IPO’d during the ZIRP era that in retrospect should never have gone public (AI accelerated some of their downfalls)…
This means that M&A has become an even more important source of liquidity and “soft landing” for companies.
One such public company is BigCommerce (recently changed name to Commerce.com):
Stock is down 97% since the IPO
Basically zero revenue growth
Barely profitable (3% NTM FCF margins and near breakeven GAAP profitable)
What is a company like this worth?
Not much…BigCommerce trades at a 0.6x NTM revenue multiple, which is the lowest of any public software company that I track. Shopify, its closest public competitor, trades at 11.5x.
During peak software stupidity (2021), BigCommerce traded at 13.5x while Shopify traded at 37x. Relatively, BigCommerce has fallen A LOT more …
A Prediction with a Meme
As I was looking at BigCommerce and thinking “these guys definitely shouldn’t be a standalone public company anymore”, I posted the below meme.
Narrator: Bending Spoons (the serial SaaS acquirer) is creepily watching BigCommerce as a potential acquisition target
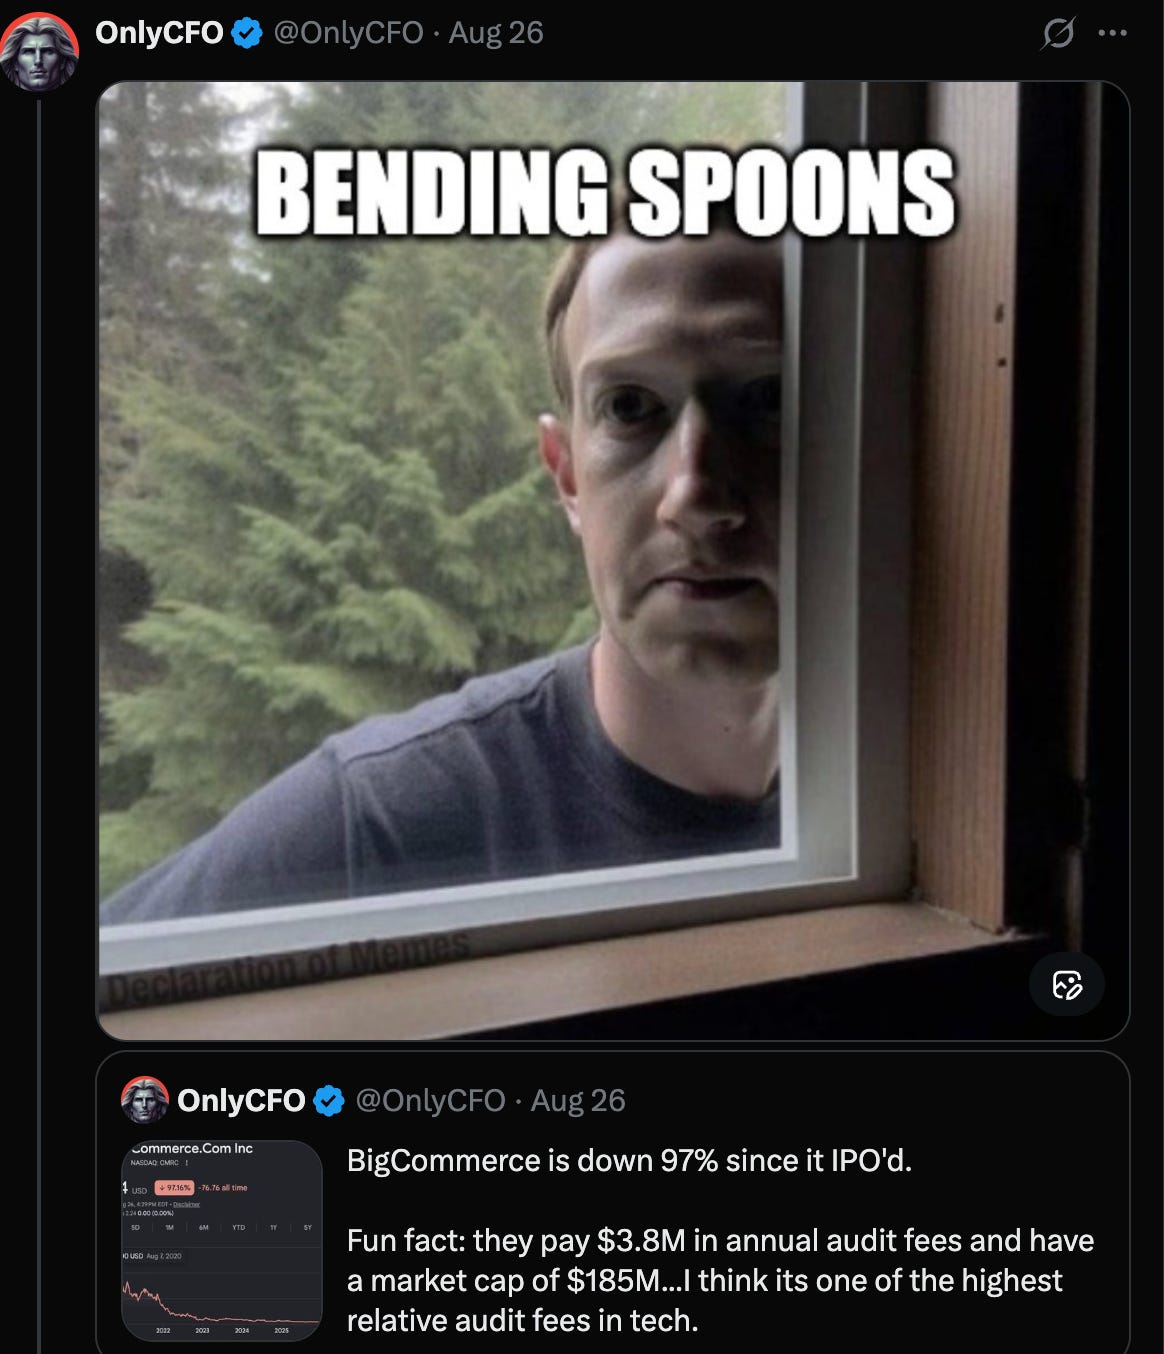
I have no idea if Bending Spoons is looking at BigCommerce (although at least a couple senior Bending Spoons folks liked the Tweet :). But…I do think it could be a decent acquisition for someone. For the right acquirer, they could probably pay up to 2x the current valuation and do well.
If you are not familiar with Bending Spoons’ game….they are a serial acquirer of digital/SaaS businesses and they IPO’d in July.
They buy struggling businesses and “transform” them into cash flow machines by cutting costs, maintaining/improving product, and usually raising product prices (by a lot sometimes).
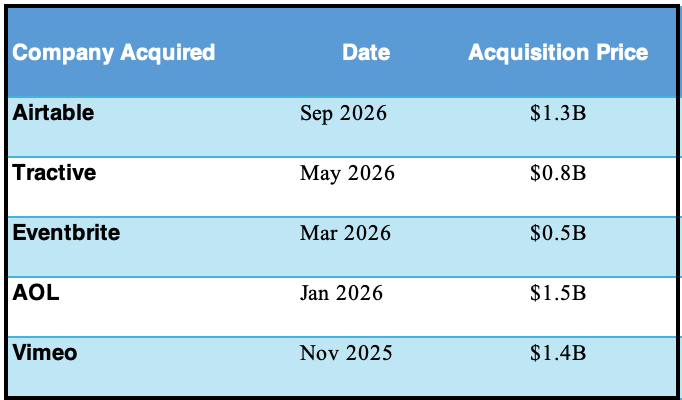
Below are some recent Bending Spoons acquisitions:
Their business sounds a lot like private equity, but with one important difference - they never plan to sell (and never have) any of the businesses that they acquire. They don’t buy with the plan to sell in 3-5 years for 3x the purchase price like PE. They get their returns by turning acquisitions into cash cows that pay for themselves (rather than relying on a future exit)
It’s not just something cheap that they are looking for. Bending Spoons wants a product that is sticky
There are two good ways to look at this from a numbers perspective:
1. RPO (Remaining Performance Obligations)
RPO represents all contracted revenue that hasn’t been recognized. It’s different than deferred revenue (which is on the balance sheet) because it also includes unbilled but contracted amounts.

BigCommerce has $201M of locked in revenue, which is crazy compared to their current $220M enterprise value….They basically have locked in future revenue equal to the company’s valuation! *note - the actual amount might be lower because customers go bankrupt or some other extreme circumstances but GAAP requires RPO to be a pretty sure thing.
Some of this future revenue is already reflected in cash because it was paid upfront though. To calculate total contracted unbilled revenue you need to subtract deferred revenue from RPO.
Since there is only $70M in deferred revenue, there is $131M of contractual billings that an acquirer would be able to invoice and collect. Pretty good relative to their valuation!

2. NRR and GRR
PE companies and acquirers like Bending Spoons will spend a lot of time here. It usually won’t be too high otherwise the company will likely be too expensive, but if it’s too low then Bending Spoons would be concerned if the unit economics break and they can’t turn it into a cash machine.
The software business model is built on high NRR and GRR (although most public companies don’t report GRR so we rely on NRR)…
During the 2021 days, BigCommerce had 118% NRR and has dropped to ~95% over the last couple of years. But at least it looks steady! And slightly improving.
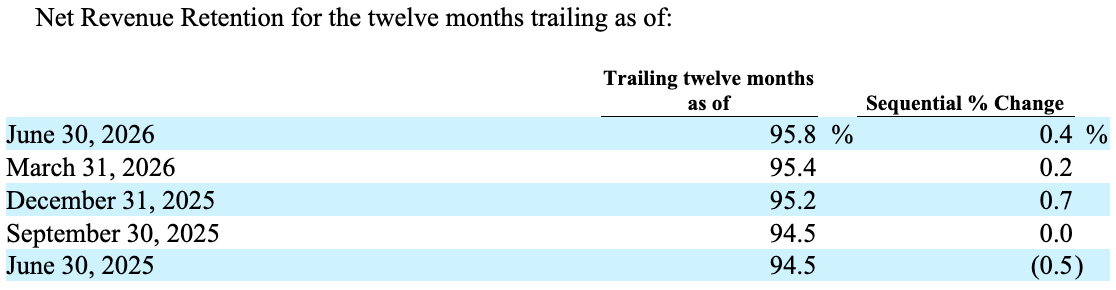
It’s not the most straightforward acquisition target for Bending Spoons, but I can definitely see a path for someone to make some money acquiring them.
BigCommerce Rejects Acquisition
A public company (Rezolve AI) actually tried to acquire BigCommerce earlier this year. Rezolve is an AI ecommerce platform so the interest made sense, but their bid apparently did not make sense to the BigCommerce board.
Rezolve’s acquisition attempt is actually pretty funny….
First Acquisition Attempt - Feb 2026
Strategy: Rezolve went to BigCommerce’s board (non-hostile)
Price: Rezolve offered 1 share for 1 BigCommerce share. The problem was Rezolve’s stock traded at $2.15 vs BigCommerce’s $3.02…a 29% discount to BigCommerce’s then-current price.
BigCommerce Board: Rejected the offer asking why shareholders would want an acquisition at a huge discount to current prices.
What’s funny is how Rezolve responded and what they did next:
Rezolve’s Response to Rejection
Rezolve didn’t hold back in their response to BigCommerce’s rejection.
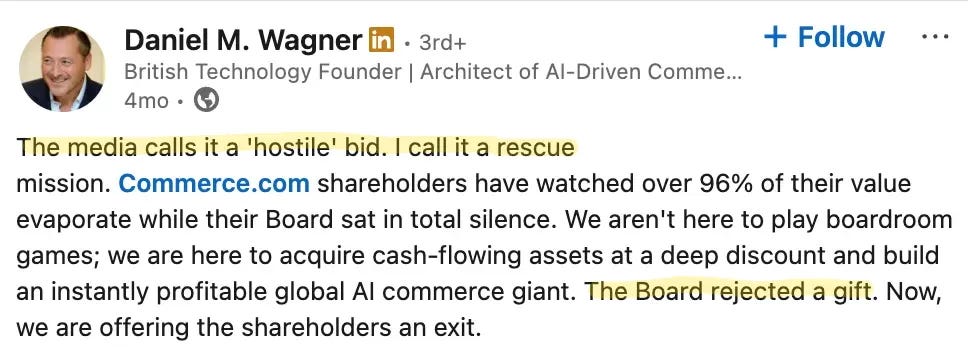
My favorite line: ”Your board rejected a gift”….lol

Rezolve argued that BigCommerce is a “zombie stock” and that the “thinly traded screen price” (stock price) was fake because the volume was so low.
Rezolve went on to say that one Wall Street analyst valued their stock at $11 (4x what they were trading at) so BigCommerce was actually getting a really good deal 🤣. You don’t see that argument every day….
Side Note: My dad recently told me he strongly believes that the OnlyCFO Newsletter is worth $1,000,000,000 so I plan to use that valuation as acquisition currency to build my finance empire.
Second Acquisition Attempt - April 2026
Since BigCommerce rejected their acquisition offer, Rezolve decided to take the offer directly to the shareholders this time (getting hostile!). They wrote an open letter to the shareholders.
But…the offer price changed :)
Rezolve’s new offer: 1 Rezolve share for 2 BigCommerce shares (deal was cut in half and represented a ~50% discount to BigCommerce’s current stock price lol)

Daniel (Rezolve CEO) refers to his bid as a “rescue” 🤣
Rejection and Adopting a “Poison Pill”
You won’t be surprised to hear that BigCommerce also rejected the new offer.
But Rezolve’s aggressiveness prompted BigCommerce to adopt a “Poison Pill” to deter any hostile takeovers. This is common once hostile takeover attempts begin.
What is a “poison pill”?
It’s a defense that makes it much more expensive for someone to acquire a company without the board’s approval.
Here is how BigCommerce’s poison pill works:
New Right: Every shareholder gets a new right attached to their shares. The right allows BigCommerce shareholders to pay $13 for $26 worth of BigCommerce stock but only if certain triggers occur (see below)
10% Threshold: Once a person/group acquires 10% ownership (20% for certain passive investors) then the new right is triggered.
Exclusion: The right is triggered for everyone except the acquirer (their right is voided). So everyone buys up a lot of stock at a discount and dilutes the potential acquirer.
In theory, an acquirer could just trigger the poison pill dilution and keep buying shares to acquire the company but that would be really expensive with a lot of unknowns. So no one actually does that.
What the hostile acquirer would do next is start a “proxy fight” to get shareholders to elect directors who support their offer and waive the poison pill. Rezolve kind of threatened a proxy fight but doesn’t seem to have actually pursued it, but they told shareholders to vote against the current board members that were up for election.
Why “Classified Boards” Matter
BigCommerce has a “classified board”, which means that there are different classes of directors that serve in staggered terms so that only a minority of directors are up for re-election in any given year.
If Rezolve attempted to continue with the hostile takeover, BigCommerce’s classified board would have also slowed them down because it would take a while for them to get board control.
What’s Next? Does Rezolve give up?
Last month, BigCommerce reported disappointing quarterly results and Rezolve made a press release that basically said “I told you so”. Rezolve didn’t provide a new acquisition offer but they suggested it would be even lower than before if they did…
BigCommerce’s stock fell ~38% over the next three days after their quarterly results. Maybe Rezolve was right?!?! Was the stock mispriced…?
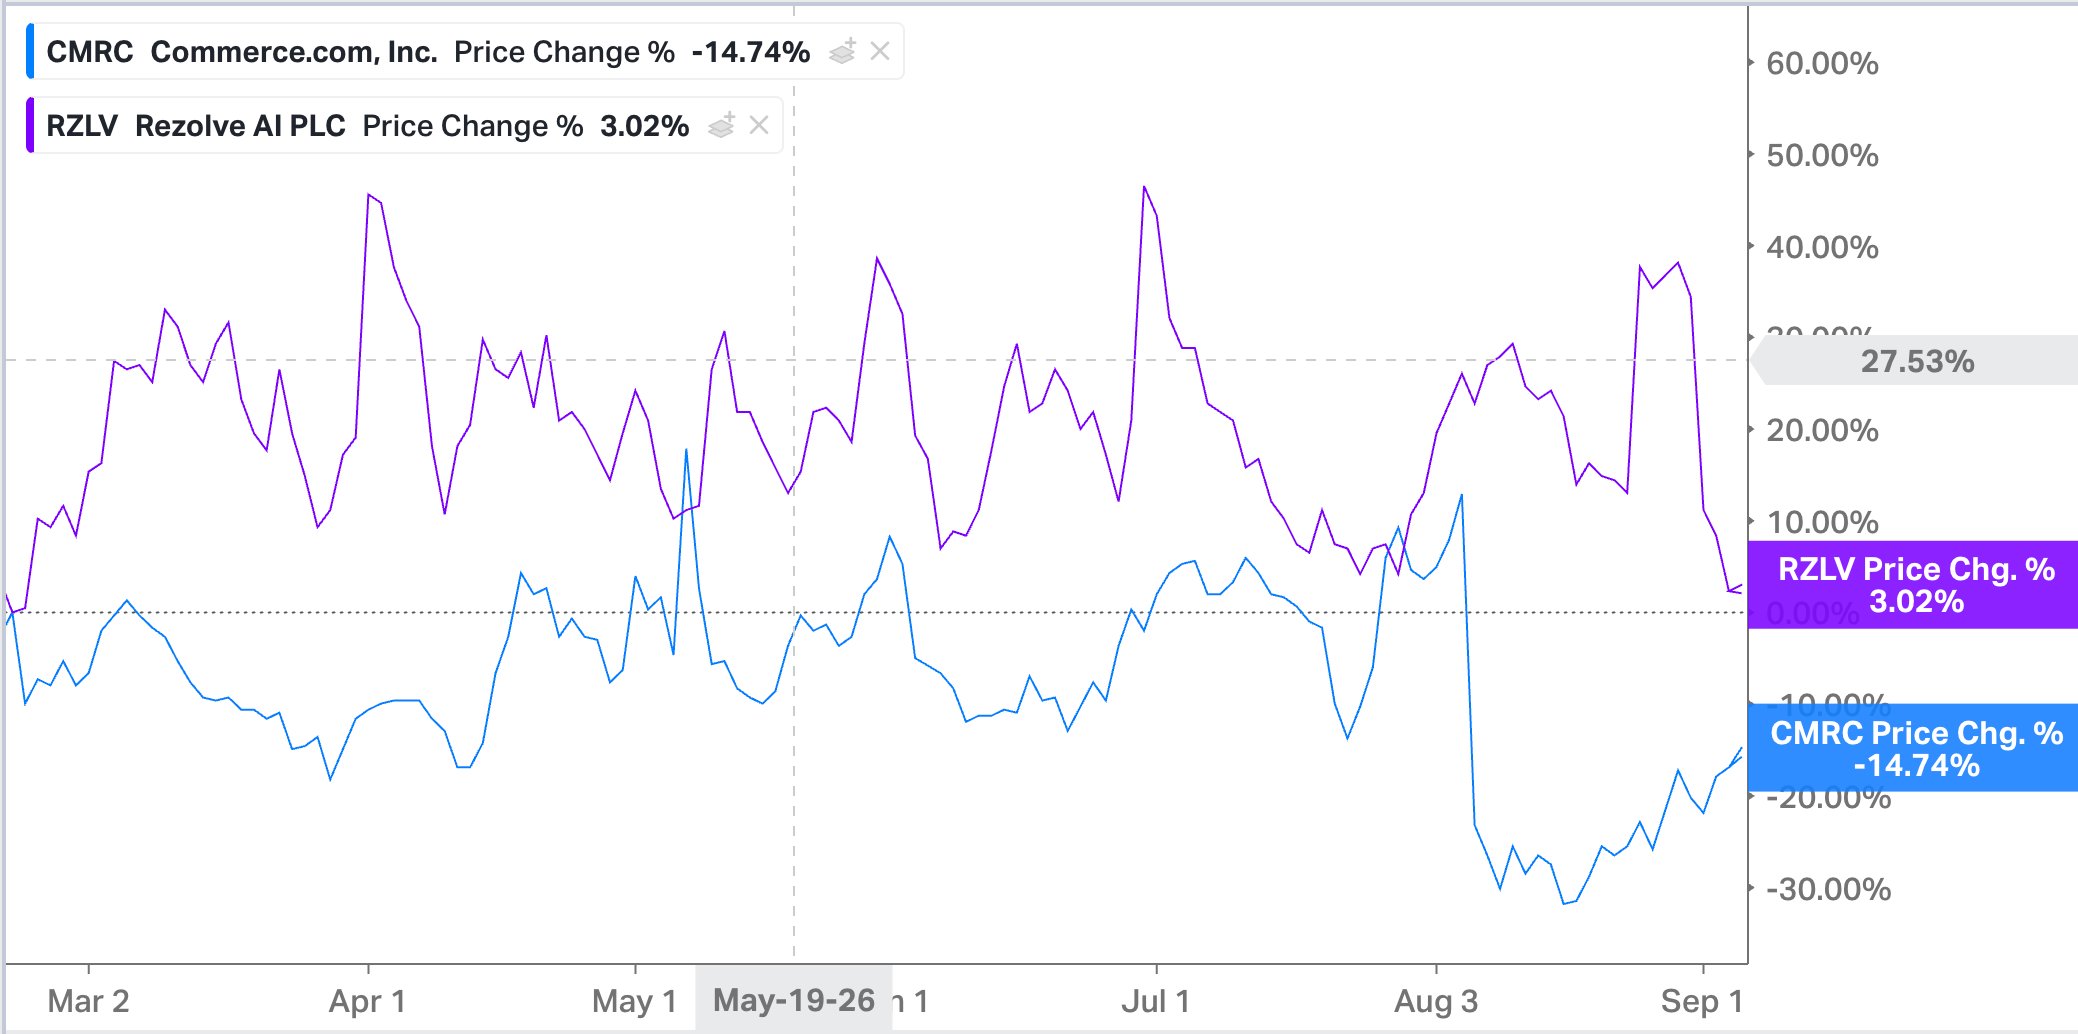
If you track the two companies’ stock prices since the original offer (1:1 share exchange), Rezolve is up only 3% (guess the Wall Street analyst was just early :) while BigCommerce is down 15%. So far, good decision by BigCommerce…
When Will BigCommerce Sell?
I don’t know a ton about BigCommerce other than their financials seem pretty broken and it would likely be more valuable if they weren’t a standalone public company (acquired by Rezolve, Bending Spoons, etc)
But obviously price matters for current equity holders.
It’s hard to see a deal like this getting done for a price below their current stock price. So acquirers will need to either:
Wait for the stock price to continue to collapse (but how much further can it fall?)
Be willing to pay a 30%+ premium from today’s price
Based on BigCommerce’s performance and continued weak outlook, I wouldn’t be surprised if something happens soon. Seems unlikely the acquirer is Rezolve based on the history though…And it will likely need to be a non-hostile acquirer given the poison pill and classified board.
Maybe someone like Bending Spoons? Maybe…
Footnotes:
Talk to my friends at Brex for a true AI-native spend platform
Subscribe and share with your friends
*Disclaimer: Informational and educational purposes only. Does not constitute investment advice. The author may own positions in companies discussed. Do your own research. Don’t make investment decisions based on anon online characters please
The RPO arithmetic is the piece's real contribution: $201M contracted against a $220M enterprise value, and after netting the $70M of deferred revenue, $131M an acquirer could still invoice and collect. At 0.6x NTM revenue the buyer is not underwriting growth at all, just collection plus a roughly 95% NRR renewal tape, which is exactly the shape a never-sell acquirer wants. And the rejected Rezolve approach supplies the missing datapoint: the board's reserve price sits somewhere above what the market currently says the company is worth.